Your Mortgage. Done Right.

APPLY NOW

We've helped thousands of Canadian buy, refinance, and renew — with zero pressure. Just honest advice that puts you first.

Mortgage financing is complicated.

Working with us isn't.

Ready to take the first step? 

The mortgage process is personal — and so is our approach. When you connect with us, we take the time to understand your goals, your finances, and your life, then map out a clear path forward that's built around you.

We've Got The Plan

There are hundreds of mortgage products out there. Finding the right one shouldn't consume your time or your peace of mind. We handle the research, comparison, and detail work — so you get a clear plan and can get back to living freely.

We've Got The Details

Arranging a mortgage involves a lot of moving parts. With 25+ years of experience, we know exactly how to bring them together — keeping you informed, prepared, and confident every step of the way. No surprises. Just results.
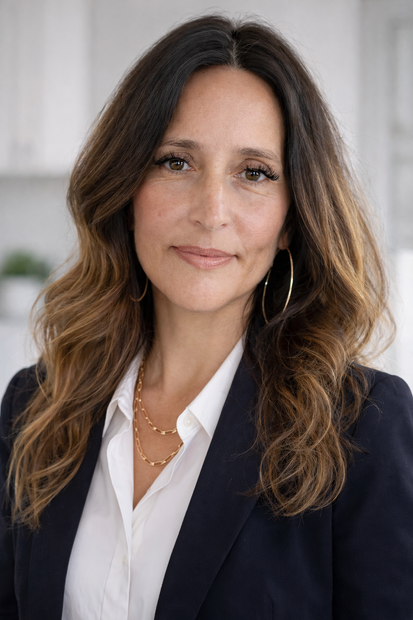
Rima Amaechi

Hi, I'm Rima. I have been privileged to be working with homebuyers and homeowners for over 25 years. Specializing in residential mortgages, there is likely no scenario I haven't seen! I will confidently guide you throughout the process, whether you are a first time home buyer or a seasoned investor.


One of my favourite parts of what I do is helping the children of past clients purchase their first homes. It’s such a privilege to support families through different stages of life and, years later, help the next generation take that exciting first step. I also have extensive experience helping clients with mortgages that are a little more “outside the box,” particularly those who have faced challenges and are looking for a fresh start.


My greatest honour is raising two amazing girls and savouring the moments as time certainly flies by. Born on Vancouver Island, with many years spent in the Kootenays, I have built an extensive network across Western Canada.

I look forward to helping you wherever life takes you across our country!


Looking forward to working with you!

CONTACT ME ANYTIME

The Mortgage Central Team,


Helping you streamline your finances, so you can live more freely, give more generously, and be present for the ones you love.

Rima is proud to be part of the Mortgage Central Team — a group of seasoned mortgage professionals with a shared mission: helping you streamline your finances so you can live more freely, give more generously, and be present for the ones you love.
APPLY NOW

Nice things people have said about working with me.

Rima’s exceptional client-service kept us sane during what otherwise would have been a stressful build-mortgage process. She always went above and beyond for us throughout our build and during our recent mortgage renewal. We appreciate Rima and recommend her to anyone who asks ‘Who did you use for your Mortgage?

M
Dain and Makenzie M

Rima is so knowledgeable and quick to answer all my questions. She gives us so much peace of mind and we've enjoyed working with her over the past 15 years

E
Challah and Scott E

This is my second time working with Rima, and we plan to remain her client for every future house purchase going forward. During my first home-buying experience as a young adult, Rima was everything you could have asked for in a mortgage broker and more. She went above and beyond to ensure I felt comfortable, knowledgeable and informed about the decisions I was making. Rima demonstrated patience and care during both home-buying experiences, and valued clear communication in every interaction. Rima responded to questions in a timely manner, often making calls and answering emails outside of a traditional work schedule to ensure her clients' needs were met without ask or hesitation. Rima was professional, organized and encouraging. We could not recommend her more for clients looking for a trusted mortgage broker who value strong work ethic and a thoughtful, personable approach.

I
Jayden and Geoff

Looking for some quick numbers?

Check out our calculators

Start by telling us where you're at in your home buying journey.
Find out what you can afford in 30 seconds >

Find out if you can afford it in 30 seconds >

Find out how much you can take out in 30 seconds >

Articles to keep you learning

By Rima Amaechi • October 15, 2026
For most Canadians, the down payment is the biggest hurdle to homeownership. A down payment is the initial amount you contribute toward your property purchase, while the lender covers the rest through a mortgage. By law, Canadian lenders can only finance up to 95% of a property’s value, which means you’ll need at least 5% down to qualify. If you’re putting down less than 20%, your mortgage must be insured through one of Canada’s three default insurance providers— CMHC, Sagen (formerly Genworth), or Canada Guaranty . This insurance comes at a cost, but it can be rolled into your mortgage amount. The less you put down, the higher the premium. Since saving a down payment can feel overwhelming, it helps to know the different sources you can draw from. Here are the most common options available to Canadian homebuyers: 1. Savings & Personal Resources The most straightforward source is your own savings. Lenders will ask to see a 90-day history of the funds in your account. Any large deposits outside of regular payroll must be explained with documentation—such as the sale of a vehicle or a transfer from an investment account. This requirement isn’t just red tape; it’s part of Canada’s anti-money laundering rules. 2. Proceeds from the Sale of a Property If you’ve recently sold another home, you can use the proceeds as a down payment on your new purchase. Proof of the sale—such as the final statement of adjustments from your lawyer—will be required. 3. RRSP Home Buyers’ Plan (HBP) First-time buyers can withdraw up to $35,000 each (or $70,000 as a couple) from their RRSPs to put toward a down payment under the federal Home Buyers’ Plan . The funds are withdrawn tax-free, but they must be repaid over a 15-year period. This is a popular option for buyers who have been steadily contributing to their retirement savings. 4. Gifted Down Payment With today’s housing prices, many buyers turn to family for help. A parent or immediate family member can provide a gift that makes up part—or even all—of the required down payment. The lender will require a signed gift letter confirming that the money is a true gift (with no repayment expected) and proof that the funds have been deposited into your account. 5. Borrowed Down Payment In some cases, you may be able to borrow your down payment. This option is usually available only if you have strong credit and sufficient income. The payments on the borrowed funds are factored into your debt service ratios, so affordability is key. Lenders typically use 3% of the outstanding balance when calculating the additional payment. The Bottom Line A down payment doesn’t have to come from just one source—it can be a combination of savings, gifted funds, RRSPs, or other resources. What matters most is being able to show where the money came from and that it meets lender requirements. If you’d like to explore your options or learn how much you might qualify for, it’s never too early to start the conversation. Connect with us today—we’d be happy to help you create a plan and take the first steps toward homeownership.
By Rima Amaechi • October 1, 2026
Co-Signing a Mortgage in Canada: Pros, Cons & What to Expect Thinking about co-signing a mortgage? On the surface, it might seem like a simple way to help someone you care about achieve homeownership. But before you sign on the dotted line, it’s important to understand exactly what co-signing means—for them and for you. You’re Fully Responsible When you co-sign, your name is on the mortgage—and that makes you just as responsible as the primary borrower. If payments are missed, the lender won’t only go after them; they’ll come after you too. Missed payments or default can damage your credit score and put your financial health at risk. That’s why trust is key. If you’re going to co-sign, make sure you have a clear picture of the borrower’s ability to manage payments—and consider monitoring the account to protect yourself. You’re Committed Until They Can Stand Alone Co-signing isn’t temporary by default. Even once the initial mortgage term ends, you won’t automatically be removed. The borrower has to re-qualify on their own, and only then can your name be taken off. If they don’t qualify, you stay on the mortgage for another term. Before agreeing, talk openly about expectations: How long might you be on the mortgage? What’s the plan for eventually removing you? Having these conversations upfront prevents surprises later. It Affects Your Own Borrowing Power When lenders calculate your debt service ratios, the co-signed mortgage counts as your debt—even if you never make a payment on it. This could reduce how much you’re able to borrow in the future, whether it’s for your own home, an investment property, or even refinancing. If you see another mortgage in your future, you’ll want to consider how co-signing could limit your options. The Upside: Helping Someone Get Ahead On the positive side, co-signing can be life-changing for the borrower. You could be helping a family member or friend buy their first home, start building equity, or take an important step forward financially. If handled with clear expectations and trust, it can be a meaningful way to support someone you care about. The Bottom Line Co-signing a mortgage comes with both risks and rewards. It’s not a decision to take lightly, but with careful planning, transparency, and professional advice, it can be done responsibly. If you’re considering co-signing—or want to explore safer alternatives—let’s connect. I’d be happy to walk you through what to expect and help you decide if it’s the right move for you.
By Rima Amaechi • September 17, 2026
Why a Mortgage Pre-Approval Protects Both Your Head and Your Heart There’s no denying it—buying a home is an emotional journey. In a competitive market, it can feel like you need to stretch beyond your comfort zone or bid above asking just to have a chance. That pressure can make it hard to separate what you want from what you can realistically afford. One of the biggest pitfalls buyers face is falling in love with a home that’s outside their price range. Once that happens, every other property seems like a compromise—even the ones that might have been a perfect fit otherwise. The best way to avoid this heartache? Get pre-approved before you start shopping. What a Pre-Approval Does for You A mortgage pre-approval gives you more than just a number—it provides clarity, confidence, and protection: Know your buying power : Shop within your true price range and avoid disappointment. Spot potential roadblocks : Uncover issues like credit bureau errors before you make an offer. Get organized : Learn exactly what documentation you’ll need so there are no surprises. Lock in a rate : Many lenders hold your rate for 30–120 days, giving you peace of mind if rates rise. Save yourself heartache : Protect yourself from falling for a home you can’t afford. Head vs. Heart Buying a home is about balance. Your head tells you what’s financially sound, your heart tells you what feels right—and both matter. A pre-approval helps bring those two sides together, so you can make confident choices without emotional stress clouding your judgment. The Bottom Line Looking at properties for fun is one thing—but if you’re serious about buying, a pre-approval is the smartest first step you can take. It sets realistic expectations, saves time, and protects your emotions along the way. If you’d like to explore your options and get pre-approved, I’d be happy to walk through the process with you. Let’s make sure you’re ready to shop with confidence.
Show More

Frequently Asked Questions

 Mortgage Financing in Cranbrook, BC

  • What does a mortgage broker do, and why should I use one instead of going to my bank?

    A mortgage broker works for you — not the bank. Rima Amaechi and the Mortgage Central Team have access to dozens of lenders, including major banks, credit unions, and private lenders, giving you far more options than walking into a single branch. With 25+ years of experience serving Cranbrook and the Kootenays, Rima shops the market on your behalf to find the best rate and terms for your unique situation — at no cost to you.

  • How much do I need for a down payment to buy a home in Cranbrook, BC?

    In Canada, the minimum down payment depends on the purchase price. Homes under $500,000 require a minimum of 5%. For homes between $500,000 and $999,999, it's 5% on the first $500,000 and 10% on the remainder. Homes over $1 million require at least 20% down. If your down payment is less than 20%, mortgage default insurance (CMHC) is required. Rima can walk you through exactly what you'll need based on your target home price in the Kootenays.

  • I'm a first-time home buyer in Cranbrook — where do I start?

    The best first step is a conversation with Rima. She'll review your income, credit, and savings to determine what you qualify for and connect you with any first-time buyer programs you may be eligible for — including the First Home Savings Account (FHSA), the Home Buyers' Plan (HBP), and BC-specific incentives. Getting pre-approved early gives you a clear budget and puts you in a stronger position when you're ready to make an offer.

  • I'm self-employed — can I still qualify for a mortgage?

    Absolutely. Self-employed Canadians can qualify for a mortgage, though the process looks a little different. Lenders typically want to see two years of self-employment history, Notice of Assessments, and business financials. Rima has extensive experience working with self-employed clients in the Kootenays and knows which lenders are most flexible for business owners, contractors, and freelancers.

  • I have bruised credit — is it still possible to get a mortgage?

    Yes. Credit challenges don't automatically disqualify you from homeownership. There are lenders who specialize in working with clients who have past credit issues, including missed payments, collections, or a previous bankruptcy. Rima will assess your full financial picture, connect you with the right lender for your situation, and in many cases, help you build a plan to strengthen your credit and qualify for better rates over time.

  • When should I think about refinancing my mortgage?

    Refinancing can make sense in several situations — to access your home equity, consolidate debt, fund a renovation, or secure a better rate. Rima will review your current mortgage terms, calculate the potential savings or costs of breaking your mortgage early, and help you decide if refinancing is the right move. If you're in Cranbrook or anywhere in the Kootenays and your financial goals have shifted since you first got your mortgage, it's worth a conversation.

  • I'm new to Canada — can I qualify for a mortgage?

    Yes. Many lenders offer mortgage programs specifically designed for newcomers to Canada, even if you have little to no Canadian credit history. Rima works with new Canadians regularly and understands which lenders offer the most flexible qualification criteria, including programs that consider international credit history and employment letters in place of traditional income documentation.

  • Can I use a mortgage to purchase an investment property in the Kootenays?

    Yes. Investment property financing is available, though the qualification requirements differ from a primary residence. Typically, a minimum 20% down payment is required, and lenders will factor in potential rental income when assessing your application. Rima can help you structure your financing strategically — whether it's your first rental property or you're growing an existing portfolio in the Cranbrook area.

  • What's the difference between a fixed and variable rate mortgage — which is better?

    A fixed rate locks in your interest rate for the term of your mortgage, giving you predictable payments. A variable rate fluctuates with the Bank of Canada's prime rate, which means your payments can go up or down. Neither is universally better — the right choice depends on your financial situation, risk tolerance, and how long you plan to stay in your home. Rima will walk you through both options and help you make a confident, informed decision.

  • How do I get started with Rima Amaechi and the Mortgage Central Team?

    Getting started is simple — just reach out directly. Rima serves clients in Cranbrook, the Kootenays, and across BC, and offers flexible consultations to fit your schedule. There's no cost, no obligation, and no pressure — just honest, experienced mortgage advice from someone who genuinely has your best interests at heart.
Still have a question?

Contact